A complimentary first meeting.
You tell us what is coming. We look at whether we are a fit for each other, and we say so either way.
Johnson Wealth Management is registered in 25 states, with offices in California, Arizona and Texas. One team handles the portfolio, the plan and the coverage, so the pieces are not working against each other.
By the time someone calls us, the money usually arrived in pieces. A retirement account from a job two jobs ago. A brokerage account somebody opened in 2011. A policy bought from a friend. A plan that made sense for a life they are not living anymore.
Nobody owns the whole picture. The investment person does not talk to the insurance person. The tax question comes up in April, when it is too late to do much about it.
And underneath it there is usually a question people feel awkward asking out loud: what am I actually paying for this, and what am I getting.
You tell us what is coming. We look at whether we are a fit for each other, and we say so either way.
Investments, planning and insurance in one view, because a decision in one shows up in the other two.
The portfolio is built for your situation, not a model everyone gets.
Quarterly, twice a year, or annually, depending on what your situation needs.
Your portfolio, your plan and your coverage are handled by the same people. You stop being the messenger between an investment person, an insurance person and a tax person who have never spoken. Nothing falls between them, because there is no between.
Our advisory account fees are published on this site: 0.125% to 0.375% a quarter, which is 0.5% to 1.5% a year. You can work out what this costs you before you ever pick up the phone.
View full fee detailsWe work with families across generations, so the plan is built to be understood by the people who inherit it, not just by the person who signed it. When your kids call, they reach a firm that already knows the history.
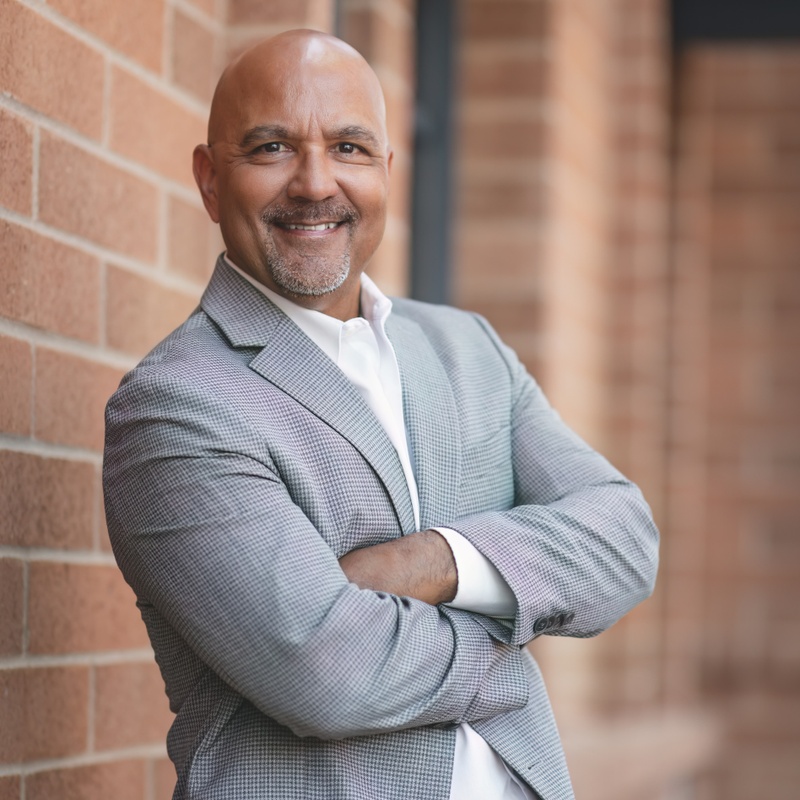
David Johnson founded Johnson Wealth Management and has advised families since 1990. He holds the Certified Financial Fiduciary designation along with the RFC, GEPC and CEA, and he carries the Series 7, 63, 65 and 24 licenses.
He was born and raised in California, married his childhood sweetheart Lisa in 1986, and has three daughters and nine grandchildren. So when we talk about a plan built to outlive the person who signed it, that is not a line we picked for a website. It is how he already thinks about money.
We have account minimums, and the first meeting is where we tell you plainly whether this is a fit. Nobody should find that out three meetings in.
Advisory accounts run 0.5% to 1.5% a year, charged quarterly. Our fees page lists how the firm is compensated, including the other products and services we offer.
You talk about what is coming. We ask about your financial picture, your goals and what you want this money to do. It is complimentary, and it works in both directions.
No. Investments, financial planning and insurance, handled together.
That is the point of meeting on a schedule. The plan is written down so it can be changed on purpose rather than in a panic.
You get the same people year after year, who know your history without reading a file. Your call does not route to whoever is on the desk today.
The hardest part of investing is not picking. It is not making an emotional decision during a bad month. That is most of what an advisor is actually for.
One team sees the whole picture, so the tax consequence of an investment decision and the gap in your coverage are noticed by the same people who can fix them.
Your first meeting is complimentary and decides fit in both directions. If we are not the right firm for you, we will say so, and you will leave knowing more than when you came in.